
 Worksheets
2026-kinfirev
Total questions: 79
Worksheet time: 40mins
What is the process of adding the items in a vertical column?
Footing
Crossfooting
Ticking
Trial balancing
What term refers to a company’s ability to pay debts as they come due?
Liquidity
Solvency
Leverage
Profitability
The ability of a business firm to satisfy its short‑term obligations as they become due is called:
Liquidity
Solvency
Capitalization
Earnings quality
The ability of a business firm to satisfy its long‑term obligations as they become due is called:
Solvency
Liquidity
Profitability
Efficiency
Two basic measures of liquidity are:
Inventory turnover and Current ratio
Current ratio and Quick ratio
Gross Profit ratio and Operating ratio
Current ratio and Average Collection period
What is the procedure set up to protect company property and equipment, ensure reliable accounting reports, promote efficiency, and encourage adherence to company policies?
Internal control
Cost accounting
Financial reporting
Auditing
Which principle says that a company must record expenses incurred to generate the revenues it reported?
Matching principle
Revenue recognition principle
Historical cost principle
Conservatism principle
During July, a company recorded: cash received 900 for services provided in July; owner cash investment 2,200; cash received 750 from a customer as partial payment of June receivables; services provided on credit 375; borrowed 6,000 by signing a promissory note; cash received 1,250 for services to be rendered next year. What was the total revenue for July?
$1,275
$2,525
$1,650
$900
At the beginning of the current year, Taunton Company’s total assets were 248,000andtotalliabilitieswere 175,000. During the year, revenues were 93,000,expenses 76,000, owner withdrawals 5,000,andtherewerenootherchanges.Atyear‑end,totalassetswere 260,000 and current assets were $63,249. What is Taunton Company’s debt ratio at year‑end (round to two decimals)?
67.31%
65.00%
32.69%
72.00%
A 15credittoSaleswaspostedasa 51 credit. What kind of error is this?
Transposition error
Slide error
Error of omission
Error of principle
On October 31, 2015, a company paid $2,400 in advance for office rent and debited Rent Expense. The lease runs for two and a half years, starting immediately. What reversing entry should be made on January 1, 2016?
Rent Expense 2,240; Prepaid Rent 2,240
Prepaid Rent 2,240; Rent Expense 2,240
Rent Expense 2,400; Cash 2,400
Prepaid Rent 2,400; Rent Expense 2,400
On December 31, an adjusted trial balance shows Accounts Receivable 24,000;InterestExpense 7,800; Commission Revenue 92,000;InterestPayable 1,500. Adjusting entries were made to accrue 4,500ofcommissionrevenueand 1,500 of interest expense. After payment of all interest due of $2,500 on January 15, what is the balance of Interest Expense?
$1,000
$2,500
$0
$1,500
On April 30, 2015, Major Inc. paid 31,500fora3‑yearfireinsurancepolicythatwouldstartafter3months.Thecompanyalsohadaremaining 25,000 balance of prepaid insurance for its car from a policy paid on February 1, 2014 for 3 years. What is the total insurance expense of the company for the year 2015?
$16,375
$31,500
$25,000
$9,375
The area of accounting aimed at serving the decision‑making needs of internal users is:
Managerial accounting
Financial accounting
Tax accounting
Governmental accounting
Which accounting guideline requires financial statement information to be supported by independent, unbiased evidence rather than someone’s belief or opinion?
Objectivity principle
Consistency principle
Materiality principle
Full disclosure principle
A complete set of financial statements for Citywide Company at December 31, 2009 would include each of the following, EXCEPT:
Balance sheet as of December 31, 2000
Income statement for the year ended December 31, 2019
Statement of projected cash flows for 2009
Notes containing additional information useful in interpreting the financial statements
A parcel of land was originally purchased for 85,000,offeredforsaleat 150,000, assessed for tax at 95,000,recognizedbypurchasersasworth 140,000, and sold for $137,000. In the seller’s books, by how much should the land account be decreased or increased to handle the sale?
Decrease $85,000
Decrease $137,000
Increase $52,000
Decrease $95,000
An example of a financing activity, EXCEPT:
Cash dividend paid
Cash dividend received
Obtaining a long‑term loan
Investment by owners
The best definition of an accounting system is:
Journals, ledgers, and worksheets
Manual or computer‑based records used to develop information for managers and others outside the organization
The personnel, procedures, devices, and records used by an entity to develop accounting information and communicate this information to decision makers
The concepts and standards specifying the information included in financial statements and how that information should be presented
At the beginning of the year, a company had 120,000ofliabilities.Duringtheyear,assetsincreasedby 160,000 and at year‑end assets equaled 360,000.Liabilitiesdecreased 20,000 during the year. Calculate the beginning and ending values of equity.
80,000and 260,000
200,000and 180,000
100,000and 300,000
140,000and 220,000
Flash reported net income of 17,500fortheyear.Assetsatthebeginningoftheyearwere 200,000 and increased by $70,000 by year‑end. Calculate the return on assets (ROA).
7.45%
8.75%
6.25%
9.00%
Major Company paid 12,960fora4‑yearinsurancepolicyonSeptember1,2013andrecordedthe 12,960 as a nominal (expense) account. What adjusting entry should be made on December 31, 2014?
Prepaid Insurance 8,640; Insurance Expense 8,640
Insurance Expense 8,640; Prepaid Insurance 8,640
Insurance Expense 3,240; Prepaid Insurance 3,240
Prepaid Insurance 3,240; Insurance Expense 3,240
A company made the following adjusting entry on December 31, 2013: Prepaid Rent 1,800; Rent Expense 1,800. If annual rent is paid in advance every October 1, what was the original transaction entry?
Rent Expense 2,400; Cash 2,400
Prepaid Rent 2,400; Cash 2,400
Cash 2,400; Rent Expense 2,400
Rent Expense 1,800; Cash 1,800
Forget Company’s Unearned Rent account had a beginning balance of 11,000andanendingbalanceof 15,000. Warehouse quarterly rent received in advance was 18,000.Duringtheyear,equipmentwasrentedtoanothercompanyatanannualrentof 9,000. Quarterly rent payments were credited to Rent Income; annual equipment rental was credited to Unearned Rent. What adjusting entry was made to arrive at the ending balance?
Rent Income 4,000; Unearned Rent Income 4,000
Unearned Rent Income 4,000; Rent Income 4,000
Rent Expense 4,000; Cash 4,000
Cash 4,000; Unearned Rent Income 4,000
A company receives interest on a $30,000, 8%, 5‑year note receivable on April 1. On December 31, 2008, the proper adjusting entry was made to accrue interest receivable. Assuming the company does not use reversing entries, what entry should be made on April 1, 2009 when the annual interest payment is received?
Cash 2,400; Interest Receivable 1,800; Interest Revenue 600
Cash 2,400; Interest Revenue 2,400
Cash 2,400; Interest Receivable 1,800; Interest Payable 600
Cash 2,400; Interest Receivable 600; Interest Revenue 1,800
The beginning of the year total equity for a firm was 40,000.Duringtheyear,thefirmissuedordinarysharesfortotalproceedsof 20,000, earned 20,000netincome,andpaid 5,000 in cash dividends. If ending total liabilities are $100,000, what are ending total assets?
$175,000
$160,000
$115,000
$140,000
Caddis Co. had these unadjusted account balances on December 31, 2009: Inventory, January 1, 2009 188,250;Purchases 142,700; Freight‑in 12,880;Purchasediscounts 2,140; Purchase returns 26,170.Assumingendinginventoryis 97,900, what adjusting entry should be made to the inventory accounts?
Cost of Goods Sold 217,080; Inventory 217,080
Inventory 217,080; Cost of Goods Sold 217,080
Cost of Goods Sold 97,900; Inventory 97,900
Inventory 321,900; Cost of Goods Sold 321,900
The use of reversing entries doesn’t change the amounts reported in the financial statements.
True
False
It is possible to reverse an incorrect entry and then prepare the correct entry.
True
False
The purpose of the post‑closing trial balance is to prove the equality of the temporary account balances carried forward into the next accounting period.
True
False
Companies record closing entries in the special journal.
True
False
The Prepaid Insurance account had a 455debitbalanceatthebeginningoftheyear; 650 of insurance premium was paid during the year; and the year‑end balance sheet showed $420 of prepaid insurance. Consequently, the income statement for the year must have shown ______ of insurance expense.
$685
$1,105
$230
$455
The office supplies account began the year with a 235debitbalance;theincomestatementshowed 475 of office supplies expense; and the year‑end balance sheet showed the current asset Office Supplies at $225. Consequently, how much office supplies must have been purchased during the year?
$465
$700
$260
$475
On December 31, Jovemel Co. correctly accrued 2,000ofsalariespayable.OnJanuary8ofthenextyear,salarieswerepaidandanadditional 1,400 of salary was incurred. The company withholds 2% of total salary for tax purposes. Assuming the correct reversing entry was made on January 1, what amounts will the compound entry on January 8 include?
Salary Expense 3,400;WithholdingTaxPayable 68; Cash $3,332
Salary Expense 2,000;WithholdingTaxPayable 40; Cash $1,960
Salary Expense 1,400;Cash 1,372
Salary Expense 3,400;WithholdingTaxPayable 0; Cash $3,400
Leomel Majer Inc. pays salaries of $10,000 every Monday for the preceding 5‑day week (Monday–Friday). Assume December 31 falls on Wednesday and the company used a reversing entry on January 1 of the next year. How much is the credit to Salaries Payable on January 5 of the next year?
$0
$6,000
$4,000
$10,000
Romabelle Co. purchased an insurance policy of 65,000in2013andmadetheadjustingentryatyear‑end:InsuranceExpense 16,250; Prepaid Insurance $16,250. If the insurance was for 3 years, when did Romabelle Co. take the policy?
April 1, 2013
January 1, 2013
July 1, 2013
October 1, 2013
Ariamel Company began 2013 with 15,000 customers billed at P10 per subscription. On April 1, 2013, the company raised its billing to P12 per subscription. Customers increased evenly during the year and totaled 16,200 at year‑end. Find Ariamel’s subscription revenue for the year ended December 31, 2013.
P166,300
P162,000
P150,000
P180,000
In November and December, Year 1, Dorr Co., a newly organized magazine publisher, received 72,000for1,000three‑yearsubscriptionsat 24 per year, starting with the January Year 2 issue. Dorr elected to include the entire $72,000 in its Year 1 income tax return. What amount should Dorr report in its Year 1 income statement for subscriptions revenue?
$0
$24,000
$72,000
$4,000
Web Services is a limited partnership. David White’s capital account began the year with a balance of 45,000.Duringtheyear,David’sshareofpartnershipincomewas 7,500, and David received $4,000 in distribution from the partnership. What is David’s partner return on equity?
16.04%
12.00%
8.50%
20.00%
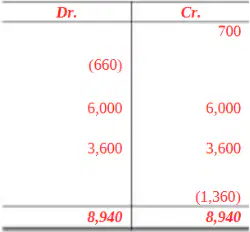
The credit total of a trial balance exceeds the debit total by 700. The following errors were determined: a credit to accounts receivable of 1,100 was not posted; a 10,000 debit to be made to the purchase account was debited to Accounts payable instead; a 6,000 credit to be made to the Sales account was credited to the Accounts Receivable account instead; the interest payable account balance of 9,000 was included in the trial balance as 10,800. How much is the correct balance of the trial balance?
14,200
14,500
14,900
15,200
Which of the following statements about adjusting entries is/are correct? Select all that apply. I. Every adjusting entry impacts both a balance sheet account and a statement of profit or loss account. II. Every adjusting entry impacts comprehensive income. III. If only year-end financial reports are prepared for both external and internal users, then adjusting entries need only be prepared once a year. IV. Adjusting entries are necessitated by accrual-basis accounting; if an entity uses the pure cash basis, there is no need for adjusting entries.
I
II
III
IV
Which of the following events is considered an internal event?
Theft
Degeneration of biological assets
Contribution by owners
Vandalism
Biden Corporation reports on a calendar-year basis. Its 2009 and 2010 financial statements contained the following errors: 2009 — over(under) statement of ending inventory (10,000); depreciation understatement 4,000; failure to accrue salaries at year-end 8,000. 2010 — over(under) statement of ending inventory 4,000; depreciation understatement 6,000; failure to accrue salaries at year-end 12,000. As a result of the above errors, 2010 income would be which of the following? Indicate amount and whether overstated or understated.
12,000 understated
20,000 overstated
24,000 overstated
24,000 understated
The following statements relate to the concept of revenue. Which statement is NOT TRUE? a. Income determination is a technical term that refers to the process of identifying, measuring and relating revenue and expenses during an accounting period. b. Transactions like issuance of capital stock and payment of dividends between the business entity and its owners cannot give rise in revenue. c. Deferred revenue is synonymous with unrealized revenue. d. The definition of income encompasses both revenue and gains.
Statement a
Statement b
Statement c
Statement d
The following information is available for Mart Company for 2010: disbursement for purchases 580,000; increase in trade accounts payable 50,000; decrease in merchandise inventory 30,000. What is the cost of goods sold for 2010?
560,000
580,000
630,000
660,000
Panda Company assigns some of its patent to other enterprises under a variety of licensing agreements. Data for 2010: Unearned revenue — 12/31/09: 500,000; 12/31/10: 1,500,000. Royalties receivable — 12/31/09: 2,000,000; 12/31/10: 2,500,000. During 2010, Panda received royalty remittances of 5,000,000. What amount of royalty income should Panda report for the year ended December 31, 2010?
3,500,000
4,000,000
4,500,000
5,000,000
A company has beginning inventory 315,638.50, inventory turnover 12.8, cash 35,236, gross profit margin 32% and profit margin 14% respectively. Operating expense is 12% of sales and the administrative expense amounted to 236,350. Income tax amounted to 321,000. What is the ending inventory of the company?
231,000
245,500
252,799
265,000
The first year of operation shows net cash receipts (disbursements) from operating, investing, and financing activities amounting to 325,700; (125,000); and 423,500 respectively. The company bought a machine worth 29,635 and furniture priced at 125,425. Cash is just a quarter of the company’s current assets, while accounts receivable is half of the current assets. What are the balances of accounts receivable and the cash receipt from investing activities, respectively?
1,248,400 and 30,060
1,248,400 and 29,635
1,294,000 and 30,060
1,294,000 and 29,635
If ending inventory is understated, the effect is to
Overstate the net purchases
Overstate the gross margin
Overstate the cost of goods available for sale
Overstate the cost of goods sold
If beginning inventory is overstated, the effect is to
Overstate net purchases
Overstate gross margin
Overstate cost of goods available for sale
Understate cost of goods sold
The overstatement of ending inventory in the current year will cause
Retained earnings to be understated in the current year-end statement of financial position
Cost of goods sold to be understated in the income statement of next year
Cost of goods sold to be overstated in the income statement of the current year
Statement of financial position not to be misstated in the next year-end
At the middle of the year, an entity paid for insurance premium for the current year and debited the amount to prepaid insurance. At year-end, the bookkeeper forgot to record the amount that had expired. In the financial statements prepared at year-end, the omission
Overstates owners' equity
Understates assets
Understates net income
Overstates liabilities
If at end of current reporting period, an entity erroneously excluded some goods from ending inventory and also these errors would cause erroneously did not record the purchase of these goods,
The ending inventory to be overstated
The retained earnings to be understated
No effect on net income, working capital and retained earnings
Net income to be understated
When the current year's ending inventory is overstated
The current year's cost of goods sold is overstated.
The current year's total assets are understated.
The current year's net income is overstated.
The next year's net income is overstated.
An overstatement of ending inventory in the current period would result in income of the next period being
Overstated
Understated
Correctly stated
The answer cannot be determined from the information
Which would result if the current year's ending inventory is understated in the cost of goods sold calculation?
Cost of goods sold would be overstated
Total assets would be overstated
Net income would be overstated
Retained earnings would be overstated
If the beginning inventory in the current year was overstated, the income for the current year would be
Understated and assets are correctly stated
Understated and assets are overstated
Overstated and assets are overstated
Understated and assets are understated
Which of the following would cause income to be overstated in the period of occurrence?
Overestimating bad debt expense
Understating beginning inventory
Overstated purchases
Understated ending inventory
Failure to record the expired amount of prepaid rent expense would not
Understate expense
Overstate net income
Overstate owners' equity
Understate liabilities
Failure to record accrued salaries at year-end results in
Overstated retained earnings
Overstated assets
Overstated liabilities
Understated retained earnings
Failure to record depreciation at year-end results in
Understated income
Understated assets
Overstated expenses
Overstated assets
Which of the following is a counterbalancing error?
Understated depletion expense
Bond premium under-amortized
Prepaid expense adjusted incorrectly
Overstated depreciation expense
Which error will not self-correct next year?
Accrued expense not recognized at year-end
Accrued revenue not recognized at year-end
Depreciation expense overstated for the year
Prepaid expense not recognized at year-end
At year-end, avas ship ordered merchandise for resale. The merchandise was shipped f.o.b. shipping point at year-end and the goods arrived early next year. The entity did not record the purchase in the current year and did not include statements for the current year were the goods in ending inventory. The effects on the financial
Income and owners' equity were correct, liabilities were incorrect, assets were correct.
Income and owners' equity were correct, assets and liabilities were incorrect.
Income, assets, liabilities and owners' equity were correct.
Income, assets, liabilities and owners' equity were incorrect.
Which of the following should not be reported retroactively?
Use of an unacceptable accounting principle and changing to an acceptable accounting principle.
Correction of an overstatement of ending inventory made in prior year.
Use of an unrealistic accounting estimate and changing to a realistic estimate.
Change from a good faith but erroneous estimate to a new estimate.
At the end of the current year, special insurance costs, incurred but unpaid, were not recorded. If these insurance costs were related to work in process, what is the effect of the omission on accrued liabilities and retained earnings, respectively, in the current year-end statement of financial position?
No effect and No effect
No effect and Overstated
Understated and No effect
Understated and Overstated
Which of the following errors would result in an overstatement of both current assets and shareholders' equity?
An understatement of accrued sales commissions
Noncurrent note receivable principal is misclassified as current asset
Annual depreciation on manufacturing machinery is understated
Holiday pay expense for administrative employees is misclassified as manufacturing overhead
At the end of the current year, an entity failed to accrue sales commissions during the current year but paid in the next year. The error was not repeated in the next year. What was the effect of the error on current year-end working capital and retained earnings, respectively?
Overstated and Overstated
No effect and Overstated
No effect and No effect
Overstated and No effect
Matrix, Inc. — Information from the records and bank statement as of July 31, 2018: Cash balance per bank P9,610; Cash balance per general ledger P7,430; Outstanding checks P2,417; Check mailed for deposit not yet reached bank P500; NSF check returned by bank P281; July interest earned per bank statement P30; Check no. 781 for supplies expense cleared the bank for P240 but was recorded in the books at P268; Deposit by Acme Company erroneously credited by the bank to our account P486. What is the adjusted cash balance?
P7,207
P7,430
P9,610
P7,237

Matrix, Inc. — Based on the July 31, 2018 bank reconciliation described (bank balance P9,610; general ledger balance P7,430; deposit in transit P500; outstanding checks P2,417; bank error P486; NSF check P281; interest earned P30; recording error on check no. 781 where bank cleared P240 but books recorded P268), which set of journal entries should be recorded to update the company’s books?
Debit Cash P30; Credit Interest Revenue P30. Debit Cash P28; Credit Supplies Expense P28. Debit Accounts Receivable P281; Credit Cash P281.
Debit Interest Revenue P30; Credit Cash P30. Debit Supplies Expense P28; Credit Cash P28. Debit Cash P281; Credit Accounts Receivable P281.
Debit Cash P30; Credit Interest Expense P30. Debit Supplies Expense P28; Credit Cash P28. Debit Accounts Receivable P281; Credit Sales Revenue P281.
Debit Cash P30; Credit Interest Revenue P30. Debit Supplies Expense P28; Credit Cash P28. Debit Notes Receivable P281; Credit Cash P281.
Donna’s Day Care — Prepare the bank reconciliation using: Cash balance per bank (June 30) P5,586; Cash balance per general ledger (June 30) P5,055; Outstanding checks P1,816; Deposit in transit P750; NSF check returned by bank P450; June interest earned P15; Check no. 800 paid by bank for P1,100 but recorded in books at P800; Deposit on books P6,000 erroneously credited on bank statement as P6,200 (bank error). What is the adjusted cash in bank?
P4,320
P5,055
P5,586
P4,170
Able Company — For the month of March, use the following: February 28 book balance 1,460,000; Note collected by bank 100,000; Interest earned on note 10,000; NSF check of customer 130,000; Bank service charge on NSF check 2,000; Other bank service charges 3,000; Outstanding checks 200,000; Deposit of February 28 placed in night depository 85,000; Check issued by Axle Company erroneously charged to Able’s account 20,000. What is the cash balance per bank statement?
1,530,000
1,435,000
1,460,000
1,515,000
Stellar Company provided the following bank statement information for December: • Ending balance, December 31: 2,800,000 • Bank service charge for December: 12,000 • Interest paid by bank to Stellar Company for December: 10,000 In comparing the bank statement to its cash records, the entity found: • Deposits made but not yet recorded by the bank: 350,000 • Checks written and mailed but not yet recorded by the bank: 650,000 The entity also discovered it had drawn and erroneously recorded a check for 46,000 that should have been recorded for 64,000. What is the cash per ledger on December 31?
2,500,000
2,520,000
2,540,000
2,480,000
Rancor Company provided the following information for December: • Balance per bank statement: 4,000,000 • Balance per cash book: 2,700,000 • Outstanding checks: 600,000 • Deposit in transit: 475,000 • Service charge: 10,000 • Proceeds of bank loan, December 1, discounted for 6 months at 12%, not recorded on company books: 940,000 • Customer’s check charged back by bank for absence of counter signature: 50,000 • Deposit of 100,000 incorrectly recorded by bank as 10,000 • Check of Rancid Company charged by bank against Rancor Company account: 150,000 • Customer’s note collected by bank in favor of Rancor Company (face 400,000; interest 40,000; collection fee 5,000): net 435,000 • Erroneous debit memo of December 28 to charge company’s account with settlement of bank loan: 200,000 • Deposit of Rancid Company credited to Rancor account: 300,000 Based on these printed facts, what is the adjusted cash balance after preparing the bank reconciliation for December?
3,980,000
4,015,000
4,050,000
4,100,000
Pathetic Company revealed the following facts on August 31: • Balance of cash in bank account: 1,300,000 • Balance of bank statement: 1,200,000 • Outstanding checks (August 31): No. 555: 10,000; 761: 55,000; 762: 40,000; 763: 25,000; 764: 65,000; 765: 70,000 • Receipts of August 31, deposited September 1: 275,000 • Bank statement charges: service charge for August: 5,000; NSF check received from a customer: 85,000 • The stub for check number 765 and the related invoice show it was for 50,000. • The check was recorded incorrectly in the cash disbursements journal as 70,000. • Payment has been stopped on check number 555 issued in payment of an account payable; the payee cannot be located. Based on these printed facts, what is the adjusted cash balance after preparing the bank reconciliation on August 31?
1,200,000
1,230,000
1,240,000
1,255,000
Basic steps in the recording process include all of the following except
Transfer the journal information immediately to the company annual report
Analyze each transaction for the effect on the accounting elements
Enter the transaction information in a journal
All of the choices are correct regarding the basic steps in the recording process
Which statement is true regarding debits and credits?
In the income statement, debits are used to increase account balances, whereas in the statement of financial position, credits are used to increase account balances
Before adjustments, debits will not equal credits in the trial balance
The rules for debit and credit and the normal balance of capital are the same as for liability
In the income statement, revenue is increased by a debit whereas in the statement of financial position, capital account is increased by a credit
Which of the following is not a possible combination of a journal entry?
Increase in asset and increase in liability
Decrease in equity and increase in liability
Decrease in liability and decrease in asset
Increase in asset and decrease in capital
A subsidiary ledger is
A listing of the components of account balances
A backup system to protect against record destruction
A listing of accounts before closing entries
A list of accounts of a subsidiary

