
 Worksheets
Econ: Supply, demand, and Price Review
Total questions: 65
Worksheet time: 39mins
Which of the following describes the relative elasticity in demand for toothpaste in a period of economic change?
Demand is inelastic because it is a luxury item.
Demand is elastic because there are no substitutes.
Demand is inelastic because it makes up a large share of most people's budget.
Demand is inelastic because it is a low-cost necessity.
A new variety of apple from imported apple trees has proved popular with American consumers. What challenge does this represent to the apple growers and their desire to take advantage of this development?
Demand for fruits such as apples is inelastic in the short run.
Demand for fruits such as apples is elastic in the short run.
Supply of fruits such as apples is inelastic in the short run.
Supply of fruits such as apples is elastic in the short run.
Which of the following is an example of how a firm can resolve the problem of diminishing marginal returns of labor?
by hiring one additional worker
by hiring several additional workers
by decreasing its marginal returns
by increasing its physical capital
Suppose a new commercial development is built, leading to the opening of several new fast-food restaurants in a market. Which of the following is the likely result of such a development?
The supply curve shifts to the left.
The supply curve shifts to the right.
The price of the good increases.
The supply of the good decreases.
Environmental regulations placed on factories by the government are likely to have this economic effect...
increase supply by increasing efficiency.
decrease supply by increasing transportation cost.
increase supply by increasing subsidy costs.
decrease supply by increasing cost of production.
What would LIKELY happen to the market for citrus fruits as a result of a severe frost in the South?
The market would be thrown into disequilibrium.
Many new sellers would enter the market.
Consumers would demand more of the fruit.
The supply curve would shift to the right.
Which of the following BEST describes equilibrium?
the point at which quantity supplied and demanded should remain no matter what happens in the market
a point on the demand curve that shows the highest market price for a good
a point on the supply curve that shows the greatest possible output
a point that moves continually in response to market changes in quantity supplied and demanded
In a market-based economy, consumers rely on prices to help them
choose among similar products.
decide which products suit their lifestyle.
discover the latest high-technology gadgets.
find clothing that fits them the best.
A huge, weeklong series of outdoor concerts is scheduled for early summer. Why will local stores LIKELY increase their supplies of consumer goods before the concert?
in response to the falling equilibrium price
in response to the expected surplus
in response to the profit incentive
in response to the supply shock

Which statement best describes the law of demand?
As price drops, people want to buy more.
As price drops, people want to buy less.
Price doesn't affect how much people want to buy of a good.
As price increases, people want to buy more.

Which of the following best explains the law of supply?
At low prices, producers want to supply more of their good.
At high prices, producers want to supply less of their good.
At high prices, producers want to supply more of their good.
Producers always want to produce as much as possible, no matter the price.

What does this graphic imply about a market economy?
Supply and demand balance each other out.
Supply is stronger/heavier than demand.
Demand is stronger/heavier than supply.
Supply and demand never interact.

According to the graph, if the price of a good increases too much, what will consumers usually do?
switch to a less expensive alternative
keep buying the good to impress their friends
demand the good in greater amounts, creating a shortage
sue the producer

What happens to quantity supplied of a product as price increases?
increases
decreases
stays the same

What is the marginal product of labor of the third employee?
11 toys
14 toys
3 toys
1 toy

Demand decreased (shifted left). What happened to the equilibrium price?
decreased
increased
stayed the same
we don't have enough information

Demand decreased (shifted left). What happened to the equilibrium quantity?
increased
decreased
stayed the same
we don't have enough information

What is the equilibrium price for a gallon of gas?
$2.20
$1.00
$1.40
$1.80

If the price of a gallon of gas is set at $2, what will happen?
shortage of 250 million gallon
surplus of 250 million gallons
shortage of 100 million gallon
surplus of 100 million gallons

What happens when the price of gas is set at $1/gallon?
shortage
surplus
equilibrium
both consumers and producers are satisfied
A price ceiling example would be Rent Control
True
False
Price that are set below the equilibrium price will likely cause a surpluses.
True
False
if the cost of a raw material goes up, we expect the supply to go up.
True
False
What kind of economic system do we use in the united states?
command
circle flow
market
free


A decrease in the price of a good will
increase supply.
have no impact
increase quantity supplied.
decrease quantity supplied.


Which statement expresses a central idea of how the laws of supply and demand work?
The government sets the prices for goods and services.
Prices are determined by the interaction of producers and consumers.
Consumers alone determine the prices for goods and services.
Technology dictates the prices charged for goods and services.


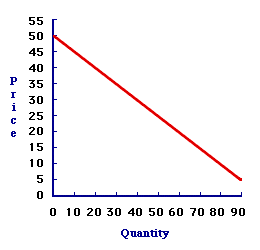

Which would an economist consider a likely substitute for coffee?
Tea
Donuts
Water
Chicken


