
 Worksheets
ACADEC ECON Unit 1 Review
Total questions: 100
Worksheet time: 1hrs 12mins
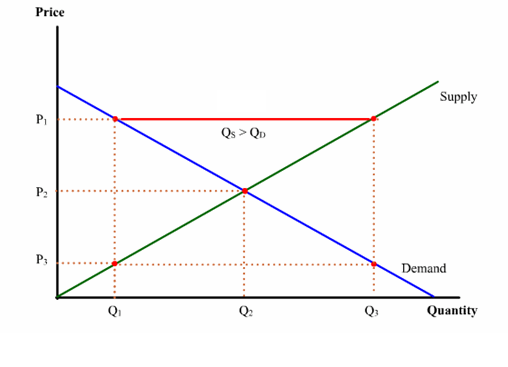
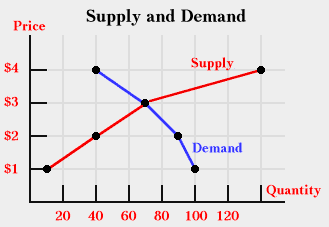

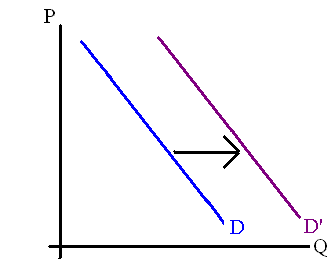


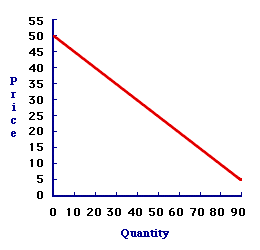

This image best represents:
An increase in demand
A decrease in demand
A decrease in quantity demanded
An increase in quantity demanded
# of sellers
supply
demand
government action
supply
demand
price/availability of resources (inputs)
supply
demand
expectations of future profit
supply
demand
technology
supply
demand
tastes & preferences
supply
demand
income
supply
demand
# of consumers (population)
supply
demand
price of related goods
supply
demand


Choose all of the statements that are TRUE regarding scarcity.
(Select all answers that apply.)
We have unlimited wants, but our resources are limited.
The goods and services we want exceed our ability to produce them.
Scarcity forces consumers, producers, and governments to make difficult choices.
Scarcity is defined as the ability to satisfy all wants at the same time. All resources and goods are unlimited.
Resources are factors of production that are used in the production of goods and services. Select all examples of resources.
production
capital
supply
natural
human
Which term below is a selection of an item or action from a set of possible alternatives?
opportunity cost
choice
production
consumption
Which term below is what is given up when a choice is made (the second-best alternative)?
opportunity cost
choice
production
consumption
Which term below is the using of goods and services?
opportunity cost
choice
production
consumption
Which term below is the combining of human, natural, capital, and entrepreneurship resources to make goods or provide services?
opportunity cost
choice
production
consumption
What are the three basic questions of economics? (Select 3.)
How will it be produced?
When will it be produced?
Why will it be produced?
For whom will it be produced?
What will be produced?
Which of the following statements are TRUE regarding a traditional economy?
(Select 2.)
Economic decisions are based on supply and demand.
Economic decisions are based on custom and historical precedent.
People often perform the same type of work as their parents and grandparents, regardless of ability or potential.
People choose their careers based on skills and preferences.
Which of the following are characteristics of a
free market economy?
(Select all answers that apply.)
private ownership of property and resources
profit motive and competition
consumer sovereignty and individual choice
lack of consumer choice
minimal government involvement in the economy
Which of the following are characteristics of a
command economy?
(Select all answers that apply.)
profit motive
consumer choice
central ownership of property and resources
centrally-planned economy with little consumer choice
competition
Which of the following are characteristics of a
mixed economy?
(Select all answers that apply.)
In the private sector, individuals and businesses are the owners and decision makers.
In the public sector, individuals and businesses are the owners and decision makers.
In the public sector, the government is the owner and decision maker.
Most economies today, including the U.S. economy, are mixed economies.
In the private sector, the government is the owner and decision maker.
In a mixed economy, which sector operates like a command economy?
public
private
both public and private
In a mixed economy, which sector operates like a free market economy?
public
private
both public and private
The key factor in determining the type of economy a country has is...
the amount of resources owned by the country.
the supply and demand of the consumers.
the price of goods and services.
the extent of government involvement in the economy.
Which type of resource is the person who has the ideas for new businesses?
natural
human
capital
entrepreneurship
Which type of resource is tools, equipment, and investment money?
natural
human
capital
entrepreneurship
Tom has been saving for a trip to Rome after college. Tom however chooses to spend the money he had been saving on graduate school. The trip to Rome is called the what of Tom's decision?
Incentive
Resource
Opportunity Cost
Scarcity
What form of economy has shared decision-making between individuals and the government? Individuals plan for the private sector, while the government plans for the public sector.
Free Market Economy
Command Economy
Mixed Economy
Traditional Economy
Every economy must face the problem of...
Profit
Consumer Sovereignty
Competition
Scarcity
Competition results in all of the following benefits to consumers EXCEPT?
Lower priced goods and services.
Better quality goods and services.
More choices in goods and services.
Lower income for employees.
The amount of money a business has remaining after it has paid all costs such as labor, rent, and utilities is known as its?
price
competition
supply
profit
Products such as fidget spinners, beanie babies, and hula hoops were extremely popular at one time and therefore were made in large number. However the demand for each has mostly disappeared so very few a made today. This is due to what principle?
Proprietorship
Consumer Sovereignty
Due Process
Opportunity Cost
The United States has many characteristics of a Free Market Economy, however the United States is actually what form of economy?
Command Economy
Traditional Economy
Mixed Economy
The interaction of supply and demand determines what?
The quality of goods and services.
The taxes placed on goods and services.
The price of goods and services.
The choices we have in goods and services.
The Law of Demand states that...
Individuals will demand more of a good or service when prices are low.
Individuals will demand less choices in goods or services.
Individuals will demand less of a good or service when prices are low.
Individuals will demand more of a good or service when quality is low.
The Equilibrium Price is the ...
The lowest that an item will sell for.
The cost of the item to be made
The price at which supply and demand meet.
The most that the government allows to be charged for that item.
The Federal Communications Commission regulates which industry in the United States?
airlines
energy
television and radio broadcast stations
professional sports
The United States government enforces anti-trust laws to -
discourage monopolies.
limit competition.
increase taxes.
provide additional public goods and services.
The radio disc jockey on Z104 aired a portion of his/her broadcast that was inappropriate and against the law. Which governmental regulatory agency will most likely levy a fine and/or penalty against the radio station?
Federal Trade Commission
Federal Communications Commission
Consumer Protection Safety Commission
Federal Deposit Insurance Corporation
If the state of Virginia decided to buy and sell goods with a foreign company, which governmental regulatory agency would be required to approve the venture?
Environmental Protection Agency
Interstate Commerce Commission
Securities and Exchange Commission
Federal Trade Commission
All are ways the government promotes marketplace competition except -
encouraging businesses to start.
passing and enforcing laws in order to prevent monopolies.
participation in global trade.
limiting small business start-up loans.
Taxes and borrowed funds are two ways that the government provides -
vacations.
news conferences.
public goods and services.
bonuses.
National Defense, Public Safety Officers, and the Postal Service are all examples of -
goods and services provided by the government.
private businesses that serve our communities.
goods and services we pay for on an as needed basis.
private businesses that are owned by individuals.
Public goods and services are those things the government provides for us because -
everybody needs them.
we are unable to provide them for ourselves.
there is a government budget surplus.
monetary policy is not working to promote economic growth.
Select all of the ways governments pay for public goods and services.
taxes
donations
fees
fines
borrowing

Which of these best explains why Mr. Darp is horizontal?
Demand in that market is perfectly elastic
Demand in that market is perfectly inelastic
Firms can sell as many units as they want for the same price
Mr. Darp is taking a nap

Which of these is NOT a characteristic of Perfectly Competitive markets?
Many small firms
Virtually identical products
High barriers to entry
No need to advertise

Which type of market have we studies in this unit?
Perfect Competition
Monopolistic Competition
Oligopoly
Monopoly

A firm expands its fixed resources and its overall costs of production go up. It is experiencing...
Increasing returns to scale
Constant returns to scale
Negative returns to scale

A firm expands its fixed resources and its overall costs of production go down. It is experiencing...
Increasing returns to scale
Constant returns to scale
Negative returns to scale
What is the best definition for Long Run?
A period of time in which at lease one resource is fixed
A period of time in which all resources can change
A period of 1 to 5 years
A period of 5 or more years
What is the best definition for Short Run?
A period of time in which at lease one resource is fixed
A period of time in which all resources can change
A period of 1 to 5 years
A period of 5 or more years

With which worker does this firm begin to experience Negative Marginal Returns?
Second
Third
Fourth
Fifth
With which worker does this firm begin to experience Diminishing Marginal Returns?
First
Second
Third
Fourth
Which of the following best explains why firms experience Increasing Marginal Returns?
Workers can specialize
Workers reach the limit of fixed resources
Managers motivate workers to produce more
Poor management leads to low motivation
Does an increase in Variable Costs affect a firm's output?
Yes
No
Maybe
Does an increase in Fixed Costs affect a firm's output?
Yes
No
Maybe
Which costs change based on the number of units produced?
Fixed
Variable
Which of the following is the best definition for Marginal Cost?
The cost of producing more units
The cost of producing one additional unit
Fixed costs
Variable Costs

According to the Profit Maximizing Formula, how many units should this firm produce?
2
3
4
5
Bob currently earns $50,000 per year as a financial planner. If he quit his job and opened an ice cream stand on the beach, earning $25,000 per year in accounting profit, what is his Economic Profit?
$25,000
$50,000
$75,000
-$25,000
What is the difference between Accounting (Normal) Profit and Economic Profit?
Merchandise Costs
Opportunity Cost
Labor Cost
Expenses
What is the Profit Maximizing Formula?
Revenue > Expenses
MR > ATC
MR = MC
AFC + AVC = ATC

